How to Evaluate Car Hauler Capacity Beyond Fleet Size
Fleet count says little about car hauler capacity. What OEM and fleet buyers should measure instead: weekly throughput, dwell, on-time pickup and subhaul control.
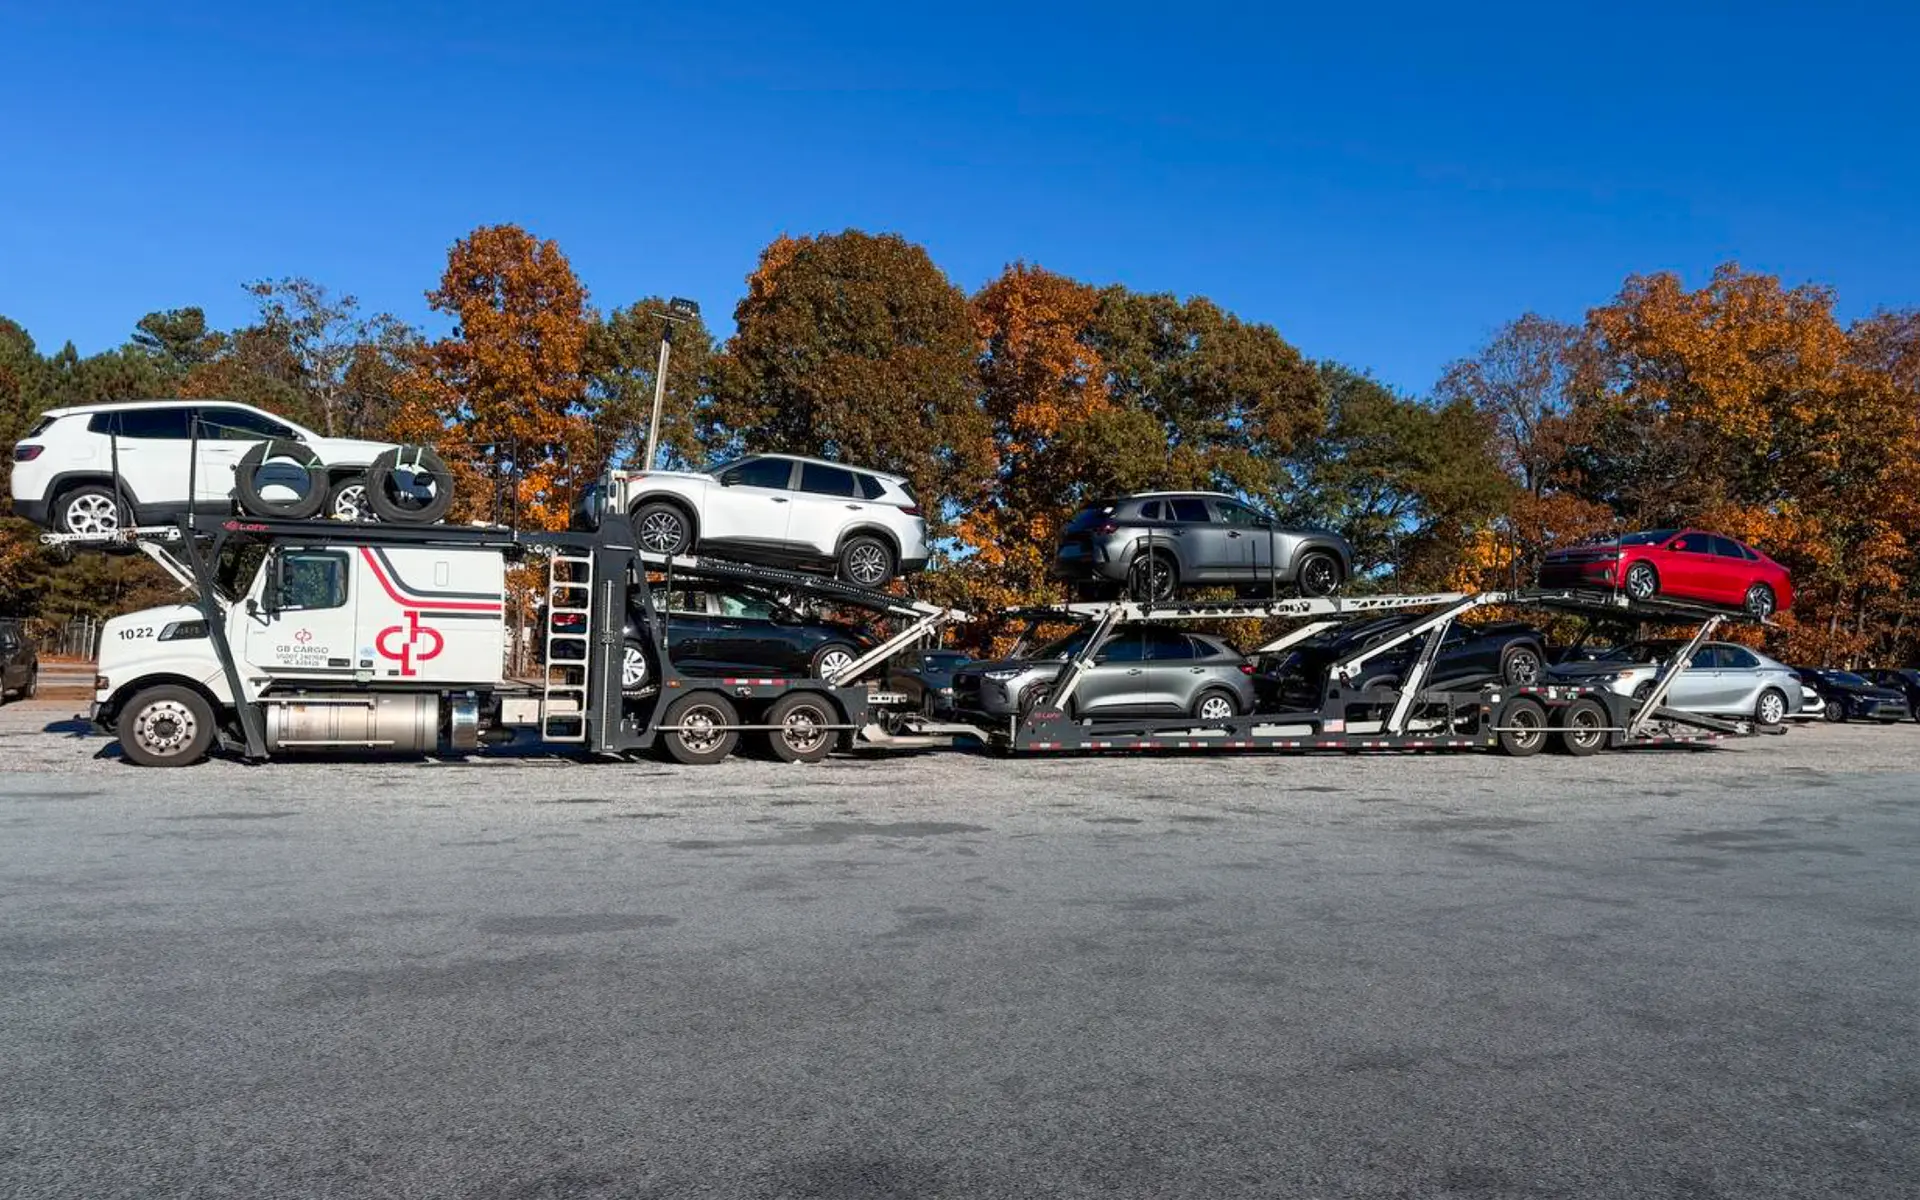
Fleet count is the easiest answer a carrier can give. It is also the least useful one when your plant releases spike and the trucks don't show up. The OEM scorecard that Ford, GM, Nissan, Stellantis and Volkswagen helped build doesn't measure fleet size at all.
It measures vehicles shipped against vehicles expected, by location, by week. That single design choice says a lot about how car hauler capacity evaluation should work. A carrier's total truck count tells you what it could do in theory. Its throughput at your origin tells you what it will actually do for you.
We are a 40-plus-truck asset-based carrier, so we have an obvious interest in this argument. That's exactly why we'll also spell out where a fleet our size is genuinely weaker, and how a buyer should test for it.
Fleet size measures a carrier's total resources, not the resources it will put at your origin. New vehicles leave from specific release points: assembly plants, port processing lots and rail ramps. The truck leg then ends at dealers or distribution points. A carrier can be large nationally and still thin at the one plant or ramp that matters to you.
That's why footprint and capacity are separate questions. Footprint is the set of origins, lanes and destination territories a carrier can credibly serve. Capacity is the volume and reliability it delivers at those places, week after week.
A useful footprint answer covers four things:
Compare two answers. "We operate in 30 states" sounds substantial, but you can't verify it against your network. "We evacuate Plant A into these dealer markets at this weekly volume" is narrower, and you can check it against your own shipment data.
Most carrier questionnaires still ask for fleet size, states served and a coverage map. Those questions are easy to answer and hard to verify. They also reward carriers for describing reach rather than proving depth.
OEM buyers have been moving away from that model. Ford's vehicle logistics leadership said in 2026 that cost "can also hide some things," and that it now weighs quality, claims handling, contract compliance and milestone data alongside price. Nissan's purchasing leadership has described its approach in terms of total delivered cost and long-term partnerships rather than lowest rate.
Evaluation also doesn't stop at the award. The AIAG scorecard exists so OEMs can track carriers after contracts are signed, and Nissan has described business reviews roughly every six months built on granular operating data. A carrier's capacity claim gets tested every week it serves the program, which is exactly why the claim should be built on location-level evidence from day one.
Car-haul capacity has swung hard in both directions over the past three years. That makes any capacity claim without a date attached unreliable. In 2024, industry discussions centered on transport capacity shortfalls across North America.
Early 2025 then reshuffled the market. Jack Cooper, which held roughly 13% of the market according to Transport Topics, lost Ford and GM within about six weeks and shut down. Its OEM freight was redistributed among the remaining carriers, and the market spent much of 2025 under rate pressure.
By mid-2026 the pendulum had swung back. Proficient Auto Logistics reported that its second-quarter volumes were "constrained by reduced available capacity following market exits," even as industry sales held close to the prior year. Trade coverage in 2026 also described a shortage of experienced auto-haul drivers hitting finished-vehicle logistics harder than other trucking segments, because the job demands specialized loading skills that take time to learn.
Volume swings aren't the only pressure. Rail disruptions change where vehicles pile up, which suddenly shifts demand for trucks to specific ramps. Model launches, model-year changeovers and restarts after plant shutdowns all change the release curve faster than dedicated trucks and drivers can be repositioned. OEM logistics leaders have described these as routine operating conditions, not rare exceptions.
The lesson for buyers is direct: capacity a carrier had during a soft market may not exist when volume returns. A claim like "we have plenty of trucks" should come with a date, a region and evidence.
The largest car haulers in recent memory are also the clearest evidence that size alone doesn't protect a buyer's network. Allied Automotive, once the largest car hauler in the U.S., went through bankruptcy in 2012, and its assets were later sold to Jack Cooper. Jack Cooper then became one of the largest finished-vehicle carriers in the country.
In February 2025, GM said Jack Cooper had unilaterally stopped service, called it a material breach, and said it had to put contingency plans in place with other providers. Jack Cooper closed within days and filed for Chapter 7 in March 2025. Scale didn't prevent the failure. It made the disruption larger when it came.
Jack Cooper's earlier history shows a second failure mode. When it emerged from Chapter 11 in 2019, management said restrictions on subcontracting had sometimes left it unable to meet peak customer demand, despite its large network. Its revised operating model specifically added the ability to bring in outside capacity when demand exceeded what its own fleet could handle.
The second misconception is that large carriers move freight mostly on their own trucks. Proficient's second-quarter 2026 results show 376,184 of its 580,962 vehicle deliveries went through its subhauler segment, which uses independent owner-operators and third-party carriers. That is roughly two-thirds of its volume.
This isn't a criticism. It's how the industry flexes. Ford's vehicle logistics leadership said in 2026 that it relies on a defined group of strategic partners and uses spot capacity at the margins, while some asset carriers add owner-operators to absorb surges.
Consolidation adds another layer. Proficient's August 2026 acquisition of Hansen & Adkins created a combined carrier that the company says will handle more than four million vehicle moves a year, roughly a quarter of the market by its own estimate. Consolidation can improve lane density and financial strength. It also concentrates a buyer's exposure: the more volume sits with one provider, the larger the hole if that provider stumbles.
So the useful question isn't "Is this carrier big enough?" It's "How much of the capacity promised to me does this carrier control, how much does it depend on others for, and who is accountable when it fails?" Small carriers aren't automatically safer either. Fleet size answers one risk, insufficient scale, and says nothing about financial health, labor stability, customer concentration or equipment condition.
The best capacity evidence is tied to your locations and is at least partly generated by your own systems. Self-reported figures are a starting point. Shipment records, timestamps and federal data are what actually prove capacity.
Operating authority and safety data are pass-or-fail checks, not differentiators. FMCSA (Federal Motor Carrier Safety Administration, the federal body that regulates commercial trucking) publishes carrier identity, size and inspection history through its SAFER system. Its SMS (Safety Measurement System, which scores carriers in safety categories called BASICs) adds percentile data. FMCSA itself cautions that SMS results are not a federal safety rating, so a buyer's threshold is a contractual choice, not a legal one.
Insurance needs the closest reading. Federal rules require $750,000 in public liability for most for-hire property carriers, but there has been no federal cargo-insurance minimum for general freight carriers since 2010. A fully loaded car hauler can carry far more value than the federal floor addresses, so "we meet DOT requirements" doesn't mean "adequately insured for this program." In our experience, most OEMs require financial, safety and insurance documentation before they award work.
Verification method matters as much as the documents themselves. FMCSA warns that even insurance certificates can be fraudulent, and it advises checking carrier contact details against SAFER rather than trusting what's on a letterhead. Asking for the COI (Certificate of Insurance) to come directly from the carrier's insurance agent closes one of the easiest gaps to exploit.
Financial durability now belongs in the same gate. Trade coverage in 2026 reported OEMs increasingly asking providers for audited financial statements, because when a carrier fails, the OEM is the one scrambling for replacement trucks.
The core metric in the AIAG (Automotive Industry Action Group) haul-away scorecard is simple: vehicles shipped per week divided by vehicles expected per week, measured by location. For an incumbent carrier, this is the most important number in a renewal. For a new carrier, the closest equivalent is its record at comparable origins with similar weekly volumes.
When you ask for this evidence, be specific. Request weekly units shipped against units tendered at one or two comparable origins over a recent stretch, how many trucks were assigned there, and how the numbers held up during the busiest weeks. Customer names can stay anonymous, but the pattern can't. A carrier that can only answer in fleet-wide averages is telling you it doesn't track performance at the level you'll measure it.
Accepting a vehicle isn't the same as moving it. The scorecard measures shippable dwell, meaning the time from final release to outgate, and dispatch reliability, meaning the share of vehicles shipped within the OEM's dispatch standard. A carrier that accepts tenders but lets releasable VINs (Vehicle Identification Numbers) age on the lot is showing weak capacity, whatever its acceptance rate says.
Dwell is also where plant reality shows up. Most plant pickups we run aren't staged: drivers search the lot or are led to each car by security, then shuttle cars to the truck. That time is part of real capacity, and our OEM customers measure our dwell and dispatch performance directly.
On-time pickups and deliveries are the measures our OEM customers score us on. We quote delivery windows rather than exact times and build buffers into them from experience, so vehicles typically arrive before the customer's deadline. Ask any carrier how it sets its delivery windows and what share of loads landed inside them last quarter.
A carrier that moves cars but can't report their status reliably weakens your ability to manage exceptions. The AIAG scorecard sets a four-hour standard for sending milestone data, subject to each OEM's contract. Our tracking runs per load, with each load's VINs listed inside it, and pickup and delivery photos become visible almost instantly once the driver marks a vehicle picked up or delivered. That is what VIN-level tracking with pickup and delivery photos should mean in practice.
Capacity that damages vehicles isn't usable capacity. The AIAG scorecard tracks damaged VINs and claims settlement, and both GM and Stellantis publicly describe quality and claims scorecard processes for carriers.
The evidence behind a damage figure matters as much as the figure. Our drivers take pickup photos right before they touch each car, and those records are timestamped, which gives both sides a clear condition baseline if a claim comes up later. Ask any carrier when its condition photos are taken and how quickly you can see them.
A smaller fleet's real risk is concentration, not size. Dedicating 10 trucks to one OEM program is about 1% of a 1,000-truck network. For a 40-truck carrier, it's a quarter of the fleet.
That matters on the days things go wrong. A truck goes down for repairs, a driver is out, or a nearby origin surges at the same time. A national carrier can usually absorb that from somewhere in its network. A smaller carrier has to have planned for it in advance.
We cover this risk by holding spare trucks, so a dedicated commitment doesn't shrink when a unit is out of service. Running newer equipment also helps, because in our experience modern car carriers spend less time in the shop. But a buyer shouldn't take that on faith from us or anyone else.
Communication is the other half of covering concentration risk. When something does go wrong, the buyer should hear about it before the window is missed, not after. On our dedicated work, changes flow from the driver to dispatch to the account manager to the customer, and the team is trained to flag problems early rather than explain them later.
Three questions test whether any carrier, large or small, has covered its concentration risk:
A smaller carrier's capacity answer is most believable when the award is geographically focused, the lanes are dense, and the volume fits its demonstrated capacity. It becomes much less believable when a proposal implies national coverage or launch-sized surges far beyond the trucks the carrier actually controls.
Subcontracting by itself isn't the red flag. Hidden subcontracting is. The AIAG scorecard states plainly that sub-haulers are the responsibility of the contracted carrier, which accepts that subhauling exists and assigns accountability for it.
Large OEM programs often run this way by design. A lead carrier or LSP (Logistics Service Provider, a company that manages transportation on the OEM's behalf) takes on the customer obligation, then qualifies third-party carriers to help fulfill it. Those qualification gates are often more explicit than OEM criteria: minimum time under operating authority, liability and cargo insurance limits, insurer ratings and safety-score thresholds. Carriers that don't meet them are told to come back once they do.
The legal line is also clear. FMCSA states that a motor carrier can't broker loads without separate broker authority, and federal rules prohibit representing brokerage as carrier operations. The risky arrangement is a load quietly passed to a carrier you never vetted, under an authority you never checked.
Our practice is straightforward. Most of our OEM freight moves on our own trucks with our own drivers. Where a contract allows it, a small portion may go to partner carriers, and those partners have to meet our sub-hauler qualification requirements first.
For any carrier offering partner capacity, ask:
A promise of "unlimited partner capacity" without those answers is a description of a phone list, not capacity.
A coverage map with large shaded regions shows theoretical reach, not capacity you can count on. The map isn't the problem. The problem is when nothing behind it explains where the trucks are based, where the drivers live, which lanes run every week, and which depend on partners.
Real depth shows up as density on specific corridors. For us, that means Midwest origins heading south and moving within the Midwest, supported by our Chicago terminal and regular runs down I-57, I-24 and I-75 toward Florida and on I-35W into Texas. The California direction is thinner for us in the current market, and we say so up front rather than shading it on a map.
Density isn't an accident. We run triangle routes between hubs, so trucks keep moving loaded instead of deadheading home. That's what makes a corridor reliable week to week: the carrier has a reason to be there regardless of any single customer's volume. When you test a carrier's footprint, ask which of your lanes fit routing it already runs, and which would need trucks pulled from somewhere else.
The same test works outside OEM programs. Auction logistics teams and buyers planning rental fleet moves can ask the same question: which of my lanes do you run every week, and which would be a one-off for you? Weekly lanes get reliable service. One-off lanes get whatever capacity happens to be free.
The stakes look different but follow the same logic. An auction coordinator working against a sale date needs units on the lot in time, not a truck that might free up later in the week. A rental fleet team moving hundreds of units out of one market needs a carrier with enough trucks on that corridor to clear the lot on schedule. In both cases, the right question is the OEM's question at a smaller scale: what will you ship from my location this week, and how do I know?
Is a smaller carrier too risky for OEM work?
Not by default. Public OEM sources don't set a universal minimum fleet size. A smaller carrier is a sound choice when the award is focused, the lanes are dense, and the carrier can show how it covers equipment and driver gaps.
Is subhauling a red flag?
Declared, contract-approved subhauling is standard industry practice. The red flag is undisclosed re-brokering, or a carrier brokering loads without broker authority.
What should a carrier's capacity proof include?
Shipped-versus-expected volume at comparable origins, dwell and dispatch performance, on-time pickup and delivery records, VIN-level status data, and verified safety and insurance documents.
Does a good SMS score mean a carrier is safe?
It's a useful signal, not a verdict. FMCSA cautions against treating SMS results as a safety rating, so pair them with inspection history, claims data and your own contractual thresholds.
How often should we re-test a carrier's capacity?
Continuously for weekly throughput, and formally whenever conditions shift: before a launch, after a shutdown, or when the market turns. A carrier's capacity in a soft market is a poor guide to its capacity in a recovery.
Buyers don't really purchase coverage. They purchase accountable throughput at specific points in their network, under conditions that rarely go to plan. Fleet size and coverage maps describe what a carrier could do. Weekly shipped-versus-expected volume, dwell, on-time performance and transparent partner arrangements show what it will do, and that holds for carriers of every size, including us.
Pick your highest-volume origin and ask every carrier you're evaluating for one thing: last quarter's on-time pickup and delivery record on comparable volume, plus how it backs up the trucks it would dedicate to you. The answers will separate paper capacity from real capacity faster than any fleet count. We're glad to answer those same questions for your lanes.
Stay informed on the latest news and insights from GB Cargo.